Brent $103, US National Debt Hits 24-Year Highs, and China's PMI Returns to Growth: Global Market Overview
On Wednesday, September 30, 2026 (data as of 12:00 Almaty time / UTC+5), markets shift focus from geopolitics to macro statistics. Oil prices sharply declined due to the restoration of Middle Eastern exports and US plans to utilize the strategic reserve.
On Wednesday, September 30, 2026 (data as of 12:00 Almaty time / UTC+5), markets shift focus from geopolitics to macro statistics. Oil prices sharply declined due to the restoration of Middle Eastern exports and US plans to utilize the strategic reserve. Meanwhile, 30-year UST yields reached a 24-year high (5.62%), and global markets are focused on today’s release of the PCE index — the Fed’s key inflation indicator.
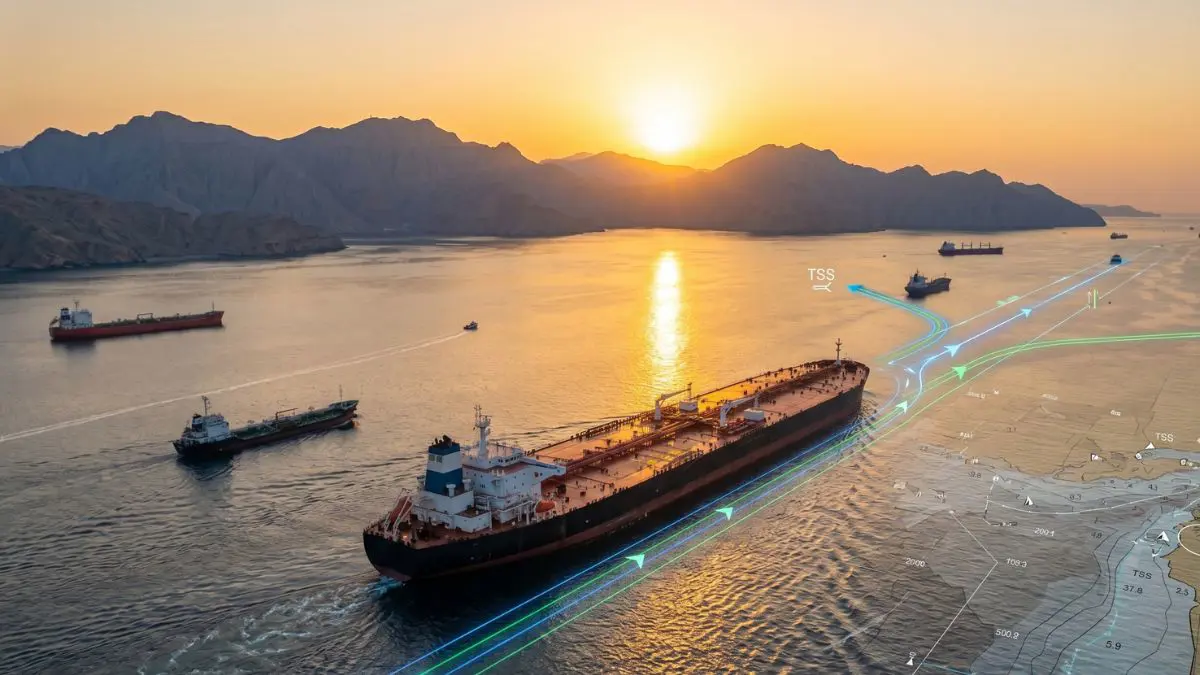
Commodities: Military Premium Removed — Brent $103, WTI Down 3.5%
Supply Recovery: Oil shipments from the Middle East have returned to 16–17.5 million b/d (98% of pre-war levels), and Saudi Arabia resumed loading at the Yanbu port. The US Department of Energy additionally offered up to 40 million barrels from the SPR, accelerating the price pullback.
SPR Auction Details: A similar offer in June attracted bids for only 500,000 barrels. If actual demand on October 6 is low, the market may see a rebound. Nevertheless, Brent has maintained gains of over 10% in September.
Macrostructure: 30-Year UST at 5.62%, Consumers Under Pressure
Debt Market Records: The yield on 30-year US Treasury bonds rose to 5.62% (highest since June 2002), while 10-year yields reached 5.282%. The market prices in a 68–70% chance of a Fed rate hike in October.
Weak US Signals: The CB Consumer Confidence Index plunged to 81.9 (a 12-year low), and JOLTS job openings fell to 7.079 million.
Corporate Front: Carnival shares soared +11.7% on strong earnings, while Fair Isaac (FICO) plunged −21.6% amid credit scoring reform.
Asia and Technology: China PMI Above 50, Mega AI Deals
Turnaround in China: The official manufacturing PMI rose to 50.1, ending a two-month decline, while the non-manufacturing PMI was 50.2. Meanwhile, Japan’s industrial production fell −1.7%, but the Nikkei (+1.0%) rose thanks to yen strengthening near the half-year close.
AI News: AMD acquired Fei-Fei Li’s startup World Labs for $8.2 billion. Meanwhile, the leaked Anthropic IPO prospectus indicated a $2 trillion target valuation with a direct warning about the technology’s “catastrophic risks.”
Calendar for Today (September 30, Almaty Time)
| Time | Event / Release | Forecast / Actual |
|---|---|---|
| — | China PMI (Manufacturing / Non-Manufacturing) | 50.1 / 50.2 (actual) |
| 17:00 | CPI Germany, France, Italy (September) | — |
| 17:15 | ADP: US Private Sector Employment | — |
| 17:30 | PCE Inflation and Core PCE US (August) | Key |
| 17:30 | Final US GDP Estimate for Q2 | — |
Practical Takeaways for Traders:
- Physical Oil Market: Diplomatic headlines give way to real supply volumes. Beware of false moves ahead of the SPR auction on October 6.
- Main Trigger — PCE at 17:30: With high expectations of a rate hike (70%), any inflation deviation will instantly move bonds, the dollar index, and gold.
- Compliance with Protocol: PCE is a high-importance event — observe the forbidden window rules (±3 minutes) to avoid slippage and penalties.