Market Review August 25: Bitcoin Breaks $80,000, Oil Falls to Lows, Investors Await Nvidia Report
Today, August 25, 2026, global markets show cautious recovery. US sanctions on Iran were milder than expected and do not yet pose an immediate threat to global oil supplies. European stocks rise,
Today, August 25, 2026, global markets show cautious recovery. The US sanctions announced against Iran were milder than expected and do not yet pose an immediate threat to global oil supplies. European stocks are rising, US futures are slightly up, oil has dropped to a weekly low, and Bitcoin has surpassed the $80,000 mark for the first time since May. Investors’ main focus is shifting to tomorrow’s Nvidia earnings report and US inflation data[cite: 2].
Stock Markets: Rebound in Europe and Tension Ahead of Nvidia Report
USA: On August 24, indices closed mixed[cite: 2]: Dow Jones rose 0.26% driven by the financial sector (JPMorgan +1.4%, Visa +3%)[cite: 2], while the S&P 500 fell 0.28% and Nasdaq declined 0.76% due to pressure on the tech sector (Nvidia -2.9%, Micron -5.8%)[cite: 2]. Auto manufacturers dropped (Ford -3.3%, GM -1.1%) amid news of tariff hikes on Canadian cars to 50% starting January 1[cite: 2]. Futures on August 25 show slight gains[cite: 2]. Nvidia’s Wednesday report remains the main focus (the market is pricing in a ±5.4% stock move or about $280 billion)[cite: 2].
Europe and Asia: STOXX 600 is up 0.3% (to ~656.14) amid mild US sanctions and strong German GDP data (+0.3%) and Ifo index (88.8)[cite: 2]. Asian markets closed mixed: Nikkei 225 gained 0.5%, while CSI 300 fell 0.2% due to continued pressure after Alibaba’s share placement[cite: 2].
Commodities Market: Oil at Weekly Low, Gold Rally Pauses
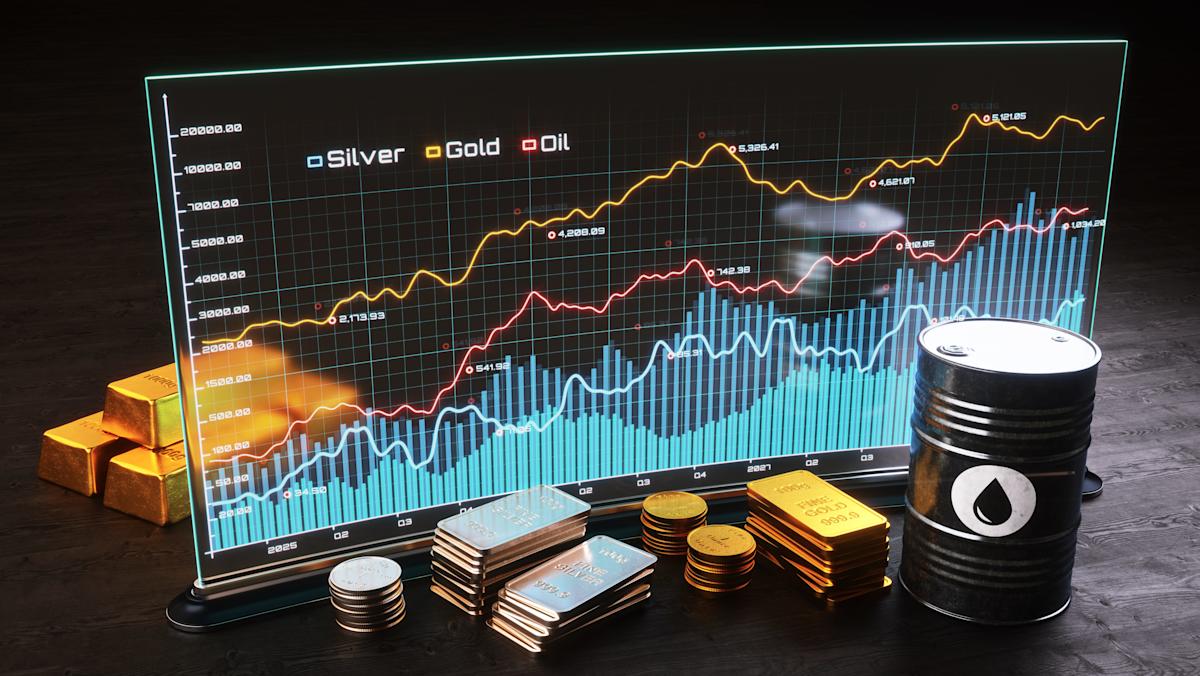
Oil: Prices dropped to weekly lows (Brent — $91.82 / -0.38%; WTI — $84.60 / -0.48%) as the US has not yet imposed broad secondary sanctions on Iran’s key trading partners[cite: 2]. However, risks remain: traffic through the Strait of Hormuz fell to a minimum (only 2 tankers on Monday)[cite: 2], and on Tuesday a tanker near Oman was damaged[cite: 2].
Precious Metals: Precious metals are taking profits amid a stronger dollar[cite: 2]. Gold fell to $4,624.87 per ounce (-0.6%)[cite: 2], silver to $67.84 (-1.6%)[cite: 2]. Yet fundamental demand remains strong: last week saw a record 10-month inflow of 46.7 tons ($6.4 billion) into gold ETFs[cite: 2].
Bitcoin Above $80,000 for First Time Since May, Dollar Recovers
Currencies and Debt: The dollar slightly recovered (EUR/USD ~1.1659, USD/JPY ~159.34)[cite: 2]. The Canadian dollar continues to weaken (USD/CAD ~1.3860) due to the trade conflict with the US[cite: 2]. The yield on 30-year US bonds remains above 5%[cite: 2], although tensions eased on news of a possible buyback of long-term securities by the US Treasury[cite: 2].
Cryptocurrencies: Bitcoin broke the $80,000 mark for the first time since mid-May, reaching a peak of $81,238[cite: 2]. The rise over the last 10 days exceeded 30%[cite: 2]. The rally is supported by expectations of favorable regulation in the US and concerns about the devaluation of traditional currencies due to US Treasury intervention in the debt market[cite: 2].
Key Events of the Week:
The key triggers this week are Nvidia’s earnings report on Wednesday, July’s PCE price index, and Fed Chair Kevin Warsh’s first speech at Jackson Hole on Friday[cite: 2].
| Day | Event |
|---|---|
| Wednesday, August 26 | Nvidia Report, July PCE Price Index, 2nd US GDP Estimate[cite: 2] |
| Friday, August 28 | Fed Chair Kevin Warsh’s Speech at Jackson Hole Symposium[cite: 2] |
Summary: The market got a temporary breather after US sanctions on Iran were less severe than expected[cite: 2]. This supported European stocks and lowered oil prices[cite: 2]. However, calm remains fragile[cite: 2]. The main test for the stock market will be Nvidia’s report, while PCE data and the Fed Chair’s speech will determine the further direction of the dollar, bonds, gold, and tech stocks[cite: 2].